5 Ways to Avoid Running Out of Money During Retirement
Let’s face it—retirement is supposed to be your reward after years of hard work, not a time spent worrying if your money will last. But if you’re like most people, the thought of running out of savings can keep you up at night.
With longer lifespans, rising healthcare costs, inflation, and unpredictable markets, it’s no wonder retirement planning feels overwhelming. But don’t worry—you’re not alone, and there are ways to take control. Instead of just thinking about how much you’ve saved, let’s talk about how you can use what you have, manage risk, and adapt to whatever comes your way.
Here are five practical, down-to-earth strategies to help you enjoy your golden years without financial stress.1. Go with the Flow: Adopt a Flexible Withdrawal Approach strategy. Things off with something that’s on everyone’s mind: how much can you safely take out each year?
The classic ‘4% rule’ says you can withdraw 4% of your savings in your first year of retirement, then bump that up for inflation each year. Sounds simple, right? But real life—and real markets—aren’t always that predictable. Here’s where flexibility comes in. If the market has a great year and your investments are up, you might treat yourself to that extra vacation or gift for the grandkids. But if things take a dip, it’s smart to tighten your belt temporarily—cut back on non-essentials and reduce withdrawals.
This way, you’re adjusting to the times and helping your money go the distance. Think of it as giving yourself permission to adapt, rather than sticking to a rigid plan.
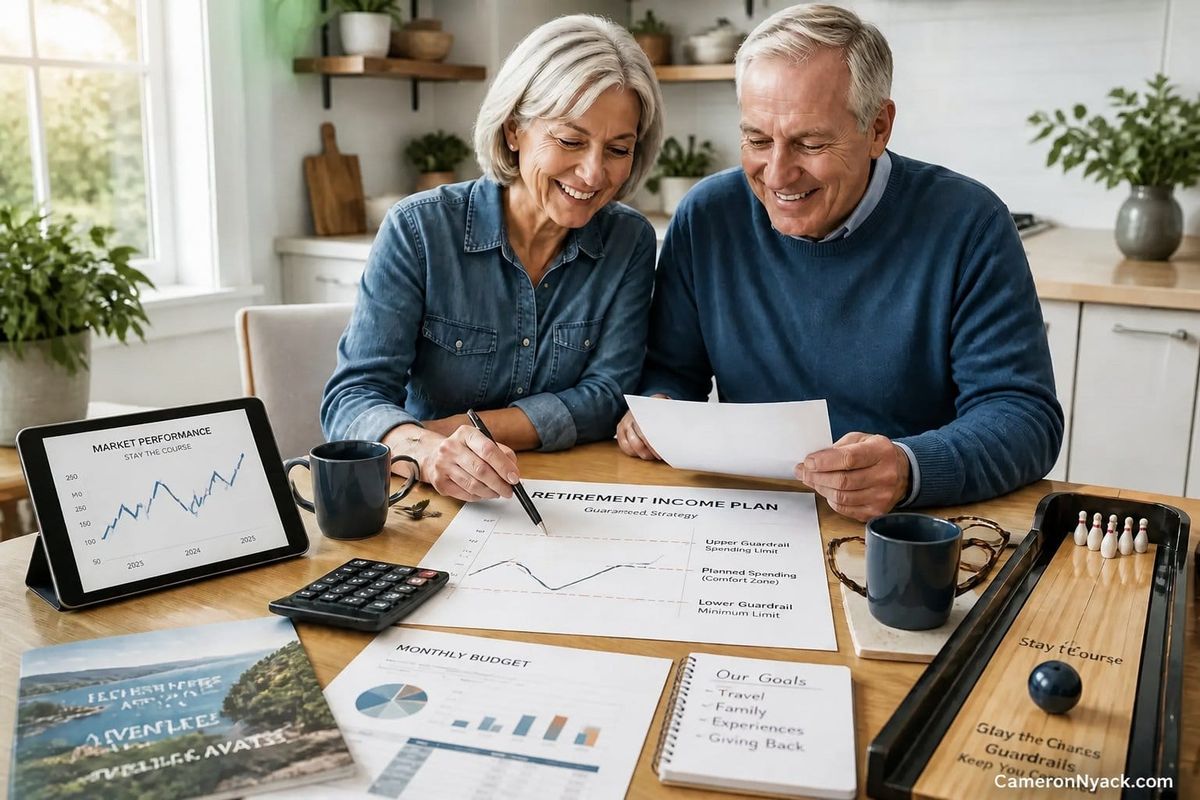
Some experts call this the “guardrails” strategy—setting upper and lower limits for your withdrawals depending on how things are going. It’s like having bumpers in a bowling alley: you’re giving yourself room to enjoy life while making sure you don’t veer too far off course. A great tip: pay for the must-haves first. Put your basic living expenses—like housing, food, and healthcare—at the top of the list. Then, see how much you can comfortably spend on the fun stuff, like travel and entertainment, depending on your finances that year.
If you remain flexible and responsive to market changes, you can extend your portfolio's life and reduce the risk of substantial asset depletion. 2. Lock In Peace of Mind: up at night, outliving your savings. Did you know there’s almost a 1-in-3 chance you’ll live past age 90 if you’re 65 today? That’s a long time to stretch your nest egg! Here’s where annuities can become your financial safety net.
By trading a lump sum for a guaranteed paycheck for life, you can add a layer of security to your retirement plan—no more guessing if your money will run out. Immediate income annuities are straightforward: make a single payment, and you start getting reliable income checks right away. It’s a great way to cover those essential living costs, so you can relax knowing your basics are taken care of.
Deferred annuities, on the other hand, let you plan for the future: you pay now (either all at once or over time), and the income kicks in later—maybe 10 or 20 years down the road. This can be a real lifesaver if you’re worried about running out of funds in your later years. The best part? The insurance company takes on the risk, so you don’t have to lose sleep over it.
Of course, not all annuities are created equal. Before you jump in, check the fees, the payout options (is it for life, or just a set number of years?), and the insurance company's reputation. Taking a little extra time to compare your options now can save you from headaches later. A well-chosen annuity doesn't have to be the only component of your retirement portfolio, since it can give you a sense of security and greatly enhance your long-term financial stability.
Supercharge Your Social Security: Wait for Bigger Checks—one of those things everyone’s heard about, but not everyone knows how best to use. When you claim your benefits matters: you can start as early as 62, but if you can hold off until 70, your monthly payments can get a serious boost. Here’s the scoop: If you wait until age 70, your monthly check could be about 76% higher than if you started at 62. That’s a lot more cash in your pocket for those later years, especially with inflation in the mix.
A bigger, inflation-adjusted payment means less stress about making ends meet—and more freedom to enjoy life. Of course, this isn’t a one-size-fits-all decision. If your health isn’t great, or if you need the money sooner, it’s perfectly okay to claim earlier. The key is figuring out what works best for your life and goals—think about your health, finances, and what you want out of retirement.
Health Comes First: Plan for Medical Costs & be honest—rising healthcare costs can feel like a giant, unpredictable storm cloud over your retirement plans. According to Fidelity’s 2026 Retiree Health Care Cost Estimate, a typical couple retiring at 65 will need about $350,000 for health care alone. That’s a big number! While Medicare lays a solid foundation, it doesn’t cover everything—think deductibles, copays, and especially long-term care.
The first step? Get to know the ABCs (and Ds) of Medicare, so you understand what’s included—and what’s not. Many retirees find peace of mind by adding a Medicare Supplement (Medigap) or Medicare Advantage plan to fill gaps and keep out-of-pocket surprises to a minimum. Don’t forget long-term care—it’s a biggie, and it can sneak up on you.
Options include buying long-term care insurance, using your own savings, or checking if you qualify for programs like Medicaid (which has strict rules). Not sure how much you’ll need? Online calculators and a chat with a financial planner can give you a realistic picture based on your health and finances. Planning early takes the panic out of the process and helps you build a solid safety net, so those surprise bills don’t throw you off course.
Unlock Your Home’s Potential: Downsize or Relocate Smartly about your home—often your biggest asset and maybe filled with decades of memories. According to the Federal Reserve, homeowners over 65 have a much higher net worth than renters, mainly thanks to home equity. If you’re open to change, downsizing (moving to a smaller, more affordable place) can free up extra cash for your retirement and even add new adventures to your life.
Here’s the upside: downsizing can shrink (or erase) your mortgage, property taxes, insurance, and maintenance bills. That means more money to live well and help your savings last. You might also consider a move to a more affordable city or state, especially if you’re craving a change of scenery or better tax benefits. Sometimes a new zip code can stretch your retirement dollars much further.
Selling a larger home can also provide a lump sum you can use for steady income, paying off debts, or building a rainy-day fund for the unexpected. Of course, downsizing or relocating isn’t for everyone. Leaving a longtime home can be tough, and it’s okay if you feel emotional about it. Chatting things through with loved ones or a counselor can help you sort out what’s right for you—financially and emotionally.
But if you’re up for it, downsizing or moving can be a powerful way to tap into your home’s value and set yourself up for a more comfortable retirement. If you clearly set out the five important strategies—that is, adopting a flexible withdrawal plan, using income annuities, putting off claiming Social Security, planning for healthcare expenses, and downsizing—you will be able to keep readers interested in practical ways of avoiding running out of money and give them more confidence in their retirement planning.
Disclaimer: The information provided is for educational and informational purposes only and does not constitute financial, investment, legal, or tax advice. We are not registered financial advisors, and the content shared should not be construed as a recommendation or solicitation to buy, sell, or hold any asset, security, or business interest.
All financial and investment decisions carry inherent risks. You should conduct your own independent research and consult with a certified financial planner, licensed professional, or legal counsel before making any financial commitments. Past performance is not indicative of future results, and you assume full responsibility for any outcomes resulting from your financial decisions.
Labels: retirement planning, avoiding running out of money, retirement savings, retirement income, longevity risk, flexible withdrawal strategy, income annuity, deferred income annuity, delayed Social Security, full retirement, rising healthcare costs, long-term care, downsizing retirement, relocation retirement, financial security.
#RetiremeSecurityng #FinancialSecurity #RetirementIncome #RetirementSavvy #FinancialWellbeing #MoneyManagement #LongevityRisk #SecureYourFuture #Downsizing #SocialSecurity